 Latent Equity
$CRWV cost of capital
Our read: $CRWV's debt got cheaper because of the mix of debt it took on, not because lenders think it's safer.
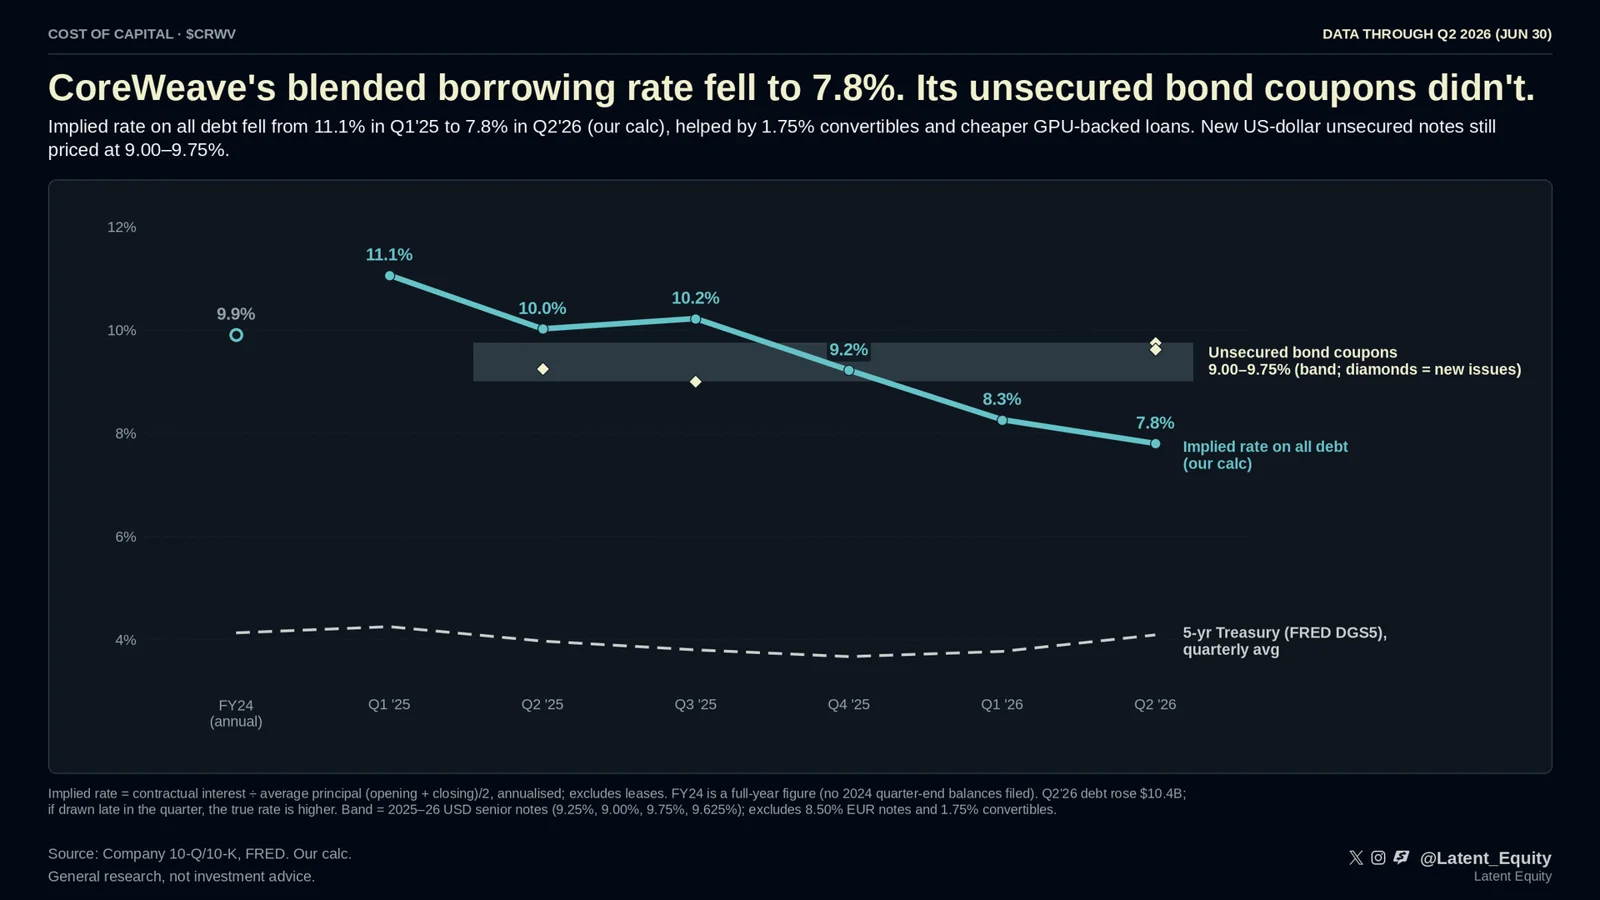
Interest paid ÷ average debt (our calc, from its filings) fell from 11.1% in Q1'25 to 7.8% in Q2'26. Its spread over the 5-year Treasury shrank from ~6.8pp to ~3.7pp.
But look at where the drop comes from:
- 1.75% convertible notes ($6.6B of $35.6B of debt at 6/30/26)
- Newer GPU-backed loans priced far lower: from SOFR+9.62% (DDTL 1.0, 2023) to SOFR+4.0–4.5% (2025–26), and SOFR+2.25% on the DDTL 4.0 Facility (Mar'26), which the company reports as non-recourse debt
- Lower SOFR (the base rate on floating loans)
New US-dollar unsecured notes still pay 9.00–9.75%, including the 2026 issues. Over the 5-year Treasury that's ~5.1–5.8pp at each issue, with no tightening (our calc, monthly averages). Our read: debt backed by contracts and collateral got cheaper; the market's view of the company's own credit didn't improve.
Caveat: Q2'26 debt rose $10.4B. Averaging opening and closing balances can skew the 7.8% if the money came in late in the quarter.
What would prove us wrong
Set before publication. We report back in public when one trips.
- the Q3'26 10-Q (due ~Nov) shows the implied rate back above ~9%, or new US-dollar unsecured coupons drop well below 9%. Open · next check: $CRWV Q3'26 10-Q (~Nov)
Method and sources
Figures marked "our calc" are our own arithmetic on the cited primary sources (company filings, earnings releases, public datasets). Every figure was checked against its source before publication.
General research, the same for every reader. Not investment advice.