 Latent Equity
SK hynix's record margin comes from memory prices, not from selling many more chips
Our read: SK hynix's record margin still comes from higher memory prices, not from selling many more chips.
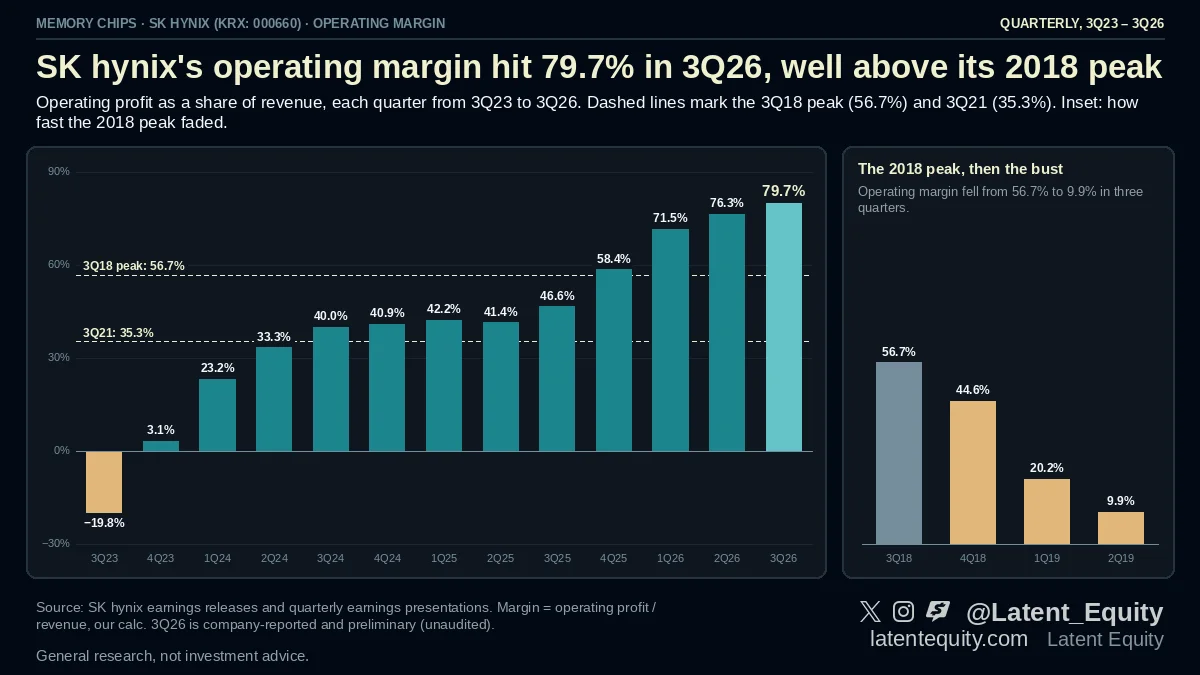
$SKHY kept 79.7% of Q3 revenue as operating profit (our calc), about 23 points above its 2018 peak of 56.7%.
Revenue was ₩104.6T, up 32% from Q2. Of the extra revenue since Q2, about 90% turned into extra operating profit.
Why it's price: DRAM, the working memory in servers and phones, shipped about 10% more chips, but its average price rose by high-20s %. NAND, the storage memory, shipped slightly less while its price rose by mid-20s %. HBM, the stacked memory next to AI chips, is part of the DRAM total; the company doesn't break out HBM's share.
Price growth is still ahead of shipment growth, but the gap narrowed, roughly 18 points vs about 22 in Q2.
History: at the 2018 peak, price growth slowed to +1%. The next quarter DRAM prices fell 11% and margin dropped 12 points.
What would prove us wrong
Set before publication. We report back in public when one trips.
- the company guides Q4 DRAM shipments up about 25%. If Q4 DRAM price growth is at or below that, the margin is no longer price-led. We check at the January report. Open · next check: SK hynix Q4 report (January 2027)
Method and sources
Figures marked "our calc" are our own arithmetic on the cited primary sources (company filings, earnings releases, public datasets). Every figure was checked against its source before publication.
General research, the same for every reader. Not investment advice.