 Latent Equity
One-day $VIX spikes say little about $SPY afterward
$VIX jumped 14% on Thursday. Does a move like that tell you anything about $SPY afterward?
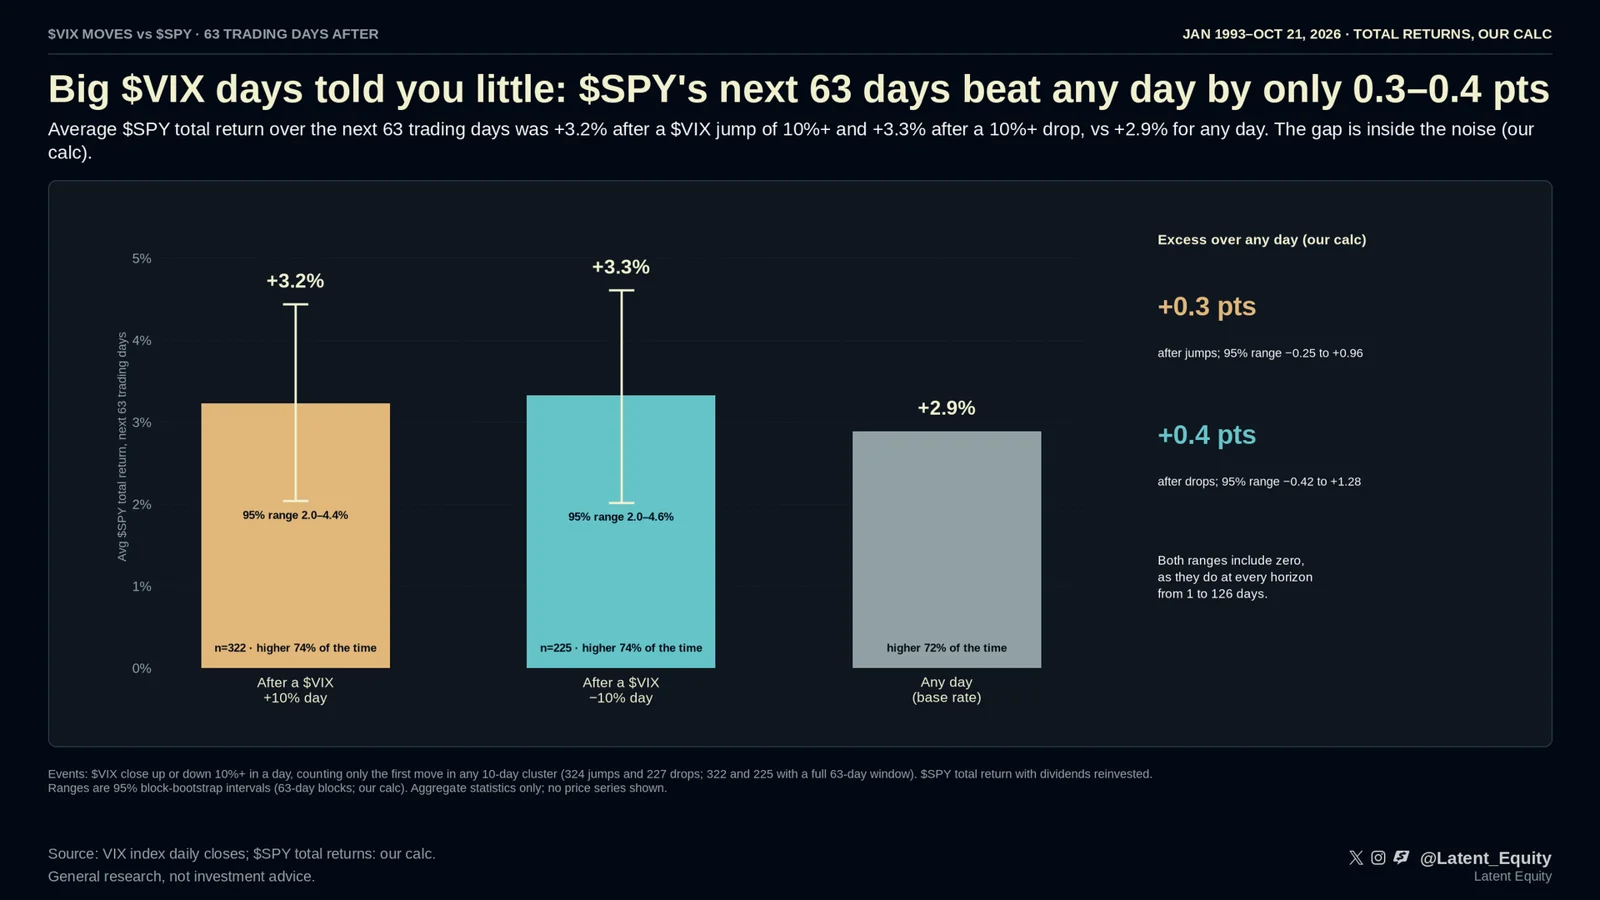
Our calc, Jan 1993–Oct 21, 2026: $VIX closed ±10% on roughly 950 days. Counting only the first move in any 10-day cluster leaves 324 jumps and 227 drops (322 and 225 with a full 63-day window since).
$SPY's average total return (dividends reinvested) was:
• After $VIX jumps: +3.2%, higher 74% of the time
• After $VIX drops: +3.3%, higher 74% of the time
• Any day: +2.9%, higher 72% of the time
The gap over a normal day (+0.3 to +0.4 pts) falls within the noise. Block-bootstrap 95% ranges (our calc) for the excess return include zero at every horizon from 1 to 126 days.
The size of the move doesn't help either. The correlation between the % change in $VIX and $SPY's forward return is near zero (0.01 to 0.12, our calc).
A one-day fear spike, on its own, has said very little about what comes next.
$VIX: Cboe via FRED. $SPY total returns: our calc.
Method and sources
Figures marked "our calc" are our own arithmetic on the cited primary sources (company filings, earnings releases, public datasets). Every figure was checked against its source before publication.
General research, the same for every reader. Not investment advice.